Eligibility
Who qualifies for private health insurance in Germany?
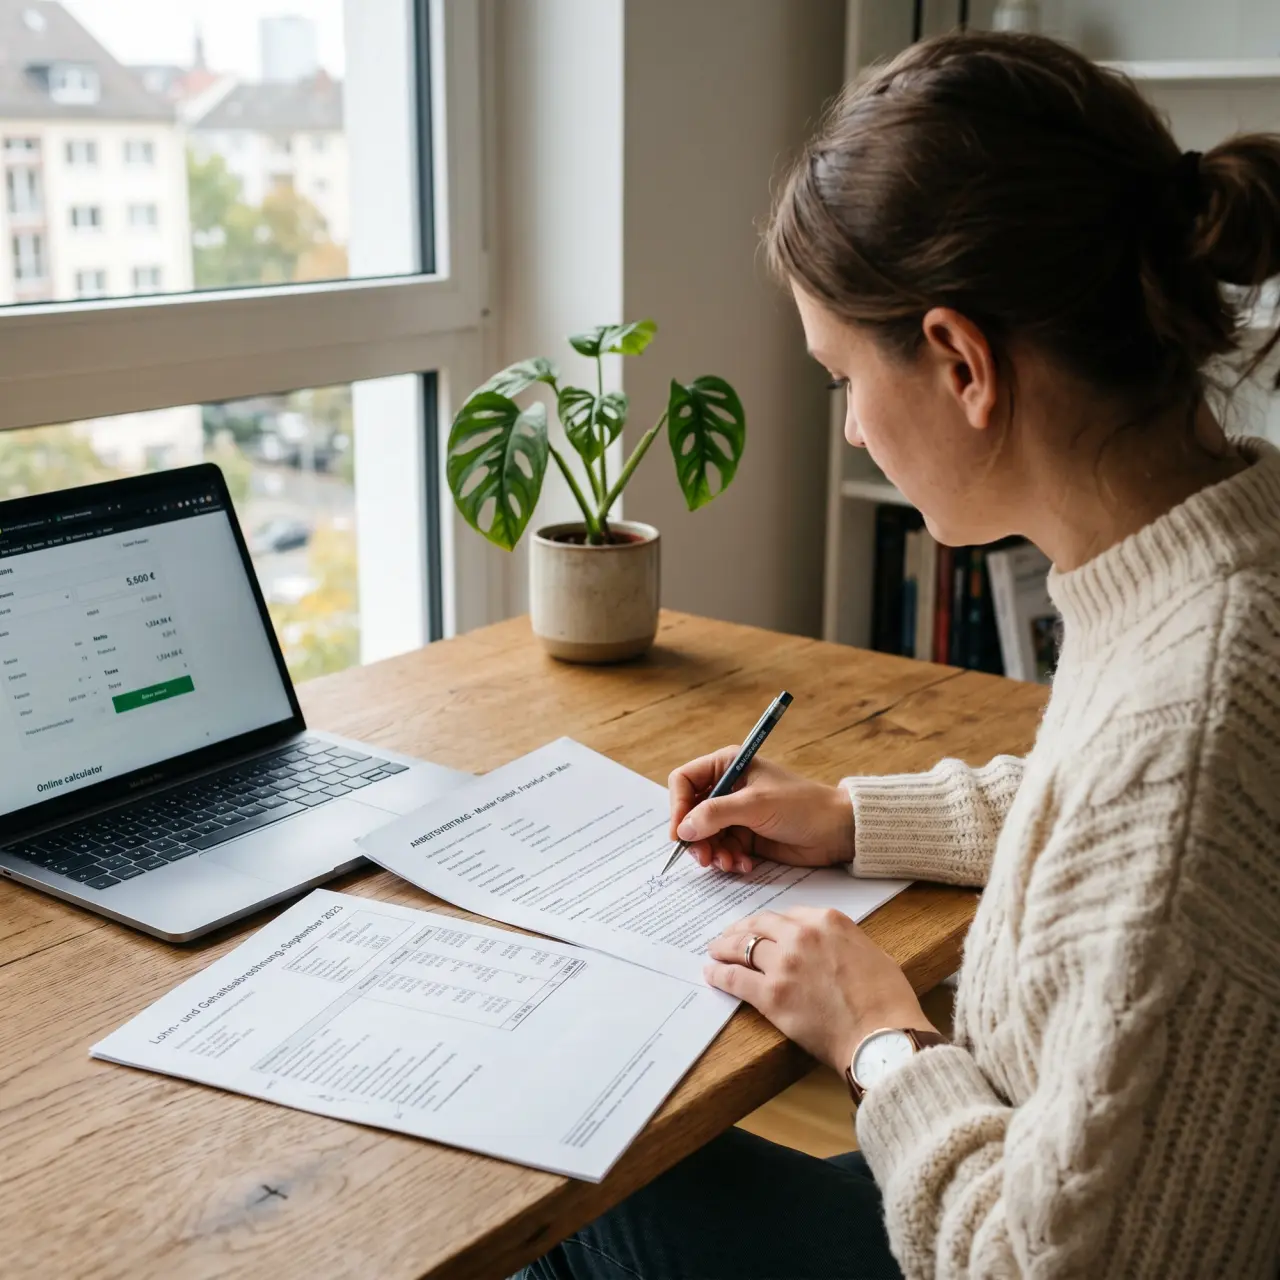
There are three paths into private health insurance: earn above €77,400, be self-employed, or be a civil servant. This page walks through each route with the 2026 numbers.
The three eligibility routes
If at least one of these applies, you can opt into private health insurance. If none applies, the public system is your only option for now.
1. Employee earning over €77,400 / year
Your gross salary must exceed €77,400 (€6,450 / month) for the current calendar year. The threshold must be cleared for three consecutive years before you can switch — though new hires above threshold can switch after one.
2. Self-employed or freelancer
If you are registered as self-employed or freelance, you can choose private regardless of income. Self-employed people are not subject to the income threshold.
3. Civil servant (Beamter)
Civil servants get half their healthcare costs covered by the state (Beihilfe) and use private to top up the other half. Almost every civil servant is in private — staying public is rarely cost-effective.
Bonus: students under 30
Until you turn 30, you can choose between public student insurance and private student tariffs. Once you finish university or turn 30, your eligibility resets to the rules above.
The one thing that decides it: your status, not your nationality
Eligibility for private health insurance has little to do with your passport and everything to do with your employment status and income. An employee only qualifies once gross pay clears the income threshold (the Jahresarbeitsentgeltgrenze, €77,400 in 2026). The self-employed and freelancers qualify at any income. Civil servants are effectively expected to go private, because the state covers half their costs. That is why two people on the same salary can have completely different options: the freelancer can choose freely, while the employee just below the line cannot. Work out which box you are in first, and the rest of the rules follow.
- Employees
Must clear €77,400 gross a year before private is even an option.
- Self-employed & freelancers
Qualify at any income. No threshold applies to you.
- Civil servants
State Beihilfe covers half, private tops up the rest.
- Students under 30
A separate, temporary route through student tariffs.
How the €77,400 income threshold actually works
For employees, this is where most of the confusion sits; our guide to private health insurance for employees also shows what you pay after the employer share. Your gross annual salary must exceed €77,400 in 2026 (about €6,450 a month). Crossing it in a single year is usually not enough on its own: the general rule is that you must be above the line for three consecutive years before you can leave public insurance. There is one important exception. If you are newly hired above the threshold from day one, or you move to Germany straight into a job that already pays above it, you can typically switch after one year, not three. Contractually guaranteed bonuses and regular overtime count toward the figure; one-off or discretionary payments do not. Miss the newcomer window and the next clean chance can be years away, so it is worth checking the timing before you sign anything.
JAEG threshold history
The Jahresarbeitsentgeltgrenze is updated each January. You must meet the threshold for the current year to opt out.
| Year | JAEG (annual) | Monthly | Δ vs. prev. |
|---|---|---|---|
| 2026 | €77.400 | €6.450 | +€3.600 (4.9%) |
| 2025 | €73.800 | €6.150 | +€4.500 (6.5%) |
| 2024 | €69.300 | €5.775 | +€2.700 (4.1%) |
| 2023 | €66.600 | €5.550 | +€2.250 (3.5%) |
| 2022 | €64.350 | €5.363 | unchanged |
| 2021 | €64.350 | €5.363 | +€1.800 (2.9%) |
| 2020 | €62.550 | €5.213 | +€1.800 (3.0%) |
Source: § 6 SGB V, official Sozialversicherungs-Rechengrößen-Verordnung published annually by the Bundesministerium für Arbeit und Soziales.
The three routes side by side
How the main routes into private health insurance compare. 2026 indicative figures.
Employee
Over the income threshold
Self-employed
Freelance or business owner
Civil servant
Beamter with Beihilfe
Getting in
Choose a plan to compare
How to confirm you actually qualify

Pin down your status
- Decide whether you are an employee, self-employed, a freelancer, a civil servant, or a student under 30.
- Your status sets which rule applies before income even enters the picture.
Check the number
- Employees: confirm your gross annual salary is above €77,400 and expected to stay there.
- Self-employed, civil servants and students under 30 can skip the threshold entirely.
Pre-check with an adviser
- We run an anonymous eligibility and health pre-check across multiple insurers.
- You get a clear answer, and the cleanest route, before anything goes on your record.
Who does not qualify, and the common edge cases
A few situations trip people up. An employee earning just under €77,400 cannot go private, even by a few euros, until they clear the line and hold it. A salary that later drops below the threshold pushes you back into public insurance. Mini-jobs and marginal employment do not count toward eligibility at all. Switching after age 55 is rarely wise, because first-time private premiums for older applicants are steep with no built-up reserves behind them. And if you are on an EU Blue Card, remember that the visa salary and the private-insurance threshold are two different numbers. When your case is not clear-cut, a short free call settles it faster than another forum thread.
Eligibility FAQs
Not sure which route is yours?
Free 15-minute call with an English-speaking adviser. We confirm whether you qualify for private health insurance, run an anonymous pre-check so nothing goes on your record, and show you the cleanest route for your status. No cost, no pressure.
Related guides
Two more pages that come up most often when people are at this stage.
What does private cost?
How premiums are priced, what changes them, and what to budget long-term.
Learn moreHow to actually switch
Step-by-step paperwork and timing for going public → private.
Learn moreThe income threshold, in detail
How €77,400 is measured, what counts, and the 3-year rule.
Learn morePrivate health insurance, explained
The full picture on cover, cost and how it works long-term.
Learn more