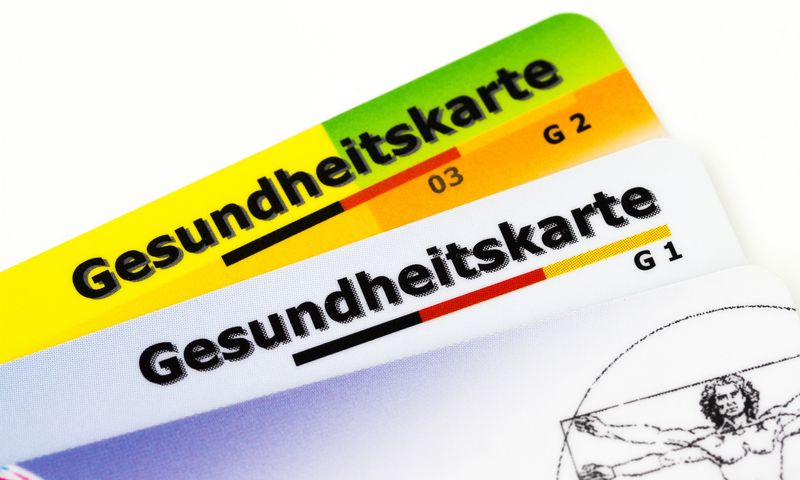
Most people choose private health insurance for the medical benefits. Fewer realise that the contributions can also lower their tax bill. For higher earners in Germany, the tax treatment of health insurance is a genuine part of the value, when it is understood properly.
Why health insurance is tax-relevant in Germany
German tax law treats health and long-term care contributions as deductible because they cover essential, basic provision, the kind of cover the state considers necessary rather than optional. This applies to both systems, but the way private cover is structured can make the deduction more meaningful for some people. Our pillar guide to Private health insurance in Germany sets the wider scene, and it is worth reading alongside this one if the tax angle is new to you.
What counts as deductible
In broad terms, the portion of your premium that pays for basic health and long-term care cover is deductible, while contributions toward extra comfort benefits are treated differently. The exact split depends on your plan, which is one reason advice matters.
Who benefits most from the tax angle
The deduction is most valuable to people on higher incomes, where each euro of deductible expense saves more tax. That tends to mean:
- high earners above the income threshold, who already pay a high marginal rate.
- the self-employed and freelancers, who carry the full contribution themselves and can plan their deductions deliberately.
- families, where multiple insured members can increase the deductible total.
For employees below the income threshold who remain in public cover, the deduction still exists, but the planning room is narrower because contributions are fixed to income and shared with the employer.
Why the structure of your plan matters for tax
Two private plans with a similar monthly premium can have very different deductible portions, depending on how much of the premium funds basic provision versus extra comfort benefits. A plan that loads heavily on optional extras may give you a smaller deductible figure than its headline cost suggests. This is not a reason to strip your cover down to the bone, but it is a reason to understand what you are buying. A plan chosen blindly on price alone can quietly leave tax value on the table, which is one more argument for comparing properly rather than signing the first reasonable offer.
How to make the most of it
Keep your annual insurance statements, which set out the deductible portions for your tax return.
Make sure your plan is structured sensibly, so you are not sacrificing useful cover purely to chase a deduction.
Coordinate the health decision with your wider tax position rather than treating it in isolation.
Comparing insurers properly also matters here, since plans differ in how their premiums break down. See our reviews on Private health insurance companies.
The role of advance payments
German tax law allows certain insurance contributions to be considered ahead of time, which can be useful for the self-employed who manage their own payments. Paying contributions in a way that aligns with your tax year, rather than haphazardly, can make the deductible portion easier to claim and your finances easier to plan. This is a detail a tax adviser can optimise once your cover is in place, but it starts with choosing a plan whose structure you understand.
A word of caution
Tax should never be the only reason to choose private cover. The medical benefits and the long-term cost are the main event, and the deduction is a welcome extra on top rather than the headline. A plan chosen mainly to shave your tax bill, but that leaves you with weaker cover or steeper premiums later, is a poor trade. We always weigh both systems honestly on public vs private health insurance before recommending anything, and the tax picture is one factor among several, not the deciding one.
Get advice tailored to your situation
Tax rules are personal, and a broker is not a substitute for a tax adviser. What we can do is help you choose cover that fits your life and your finances. We start with a free consultation by phone. Request a free quote to begin, and bring your tax questions with you.
 Written byMarco Maurelli
 Reviewed byBettina Ostermann