Upgrade from public health insurance to Premium private health insurance: 2026 Guide
Yes, you can upgrade from public health insurance to a premium private health insurance plan, provided you earn above the 2026 Jahresarbeitsentgeltgrenze (JAEG), the income threshold, as an employee, or you are self-employed or a civil servant, in which case the income threshold does not apply to you at all.
If you are under 40, single, and healthy, the numbers usually favor private health insurance. If you have a non-earning spouse and children, the math shifts considerably because each family member needs a separate premium. The step-by-step checklist is in Section 6, and the age-55 risk is covered in Section 5.
Table of Contents
- How does public health insurance compare to premium private health insurance at a glance?
- Who should consider switching to private health insurance?
- What do private health insurance premiums actually cost, and how does the employer subsidy change the math?
- What are the real pros, cons, and long-term risks of going private?
- How do you actually switch from public health insurance to private health insurance, step by step?
- How do you choose the right premium private plan?
- Real-world scenarios: how the numbers play out in practice
- Key Takeaways
- What I tell clients before they decide
- Useful sources and where to get help
- Myhealthcarebroker makes the private health insurance switch straightforward for high earners
How does public health insurance compare to premium private health insurance at a glance?
The two systems operate on fundamentally different logic. Public health insurance charges a percentage of your income; private health insurance charges based on your age, health, and the coverage tier you choose. For a high earner, that distinction changes the monthly numbers significantly.
| Dimension | Public health insurance (Statutory) | Premium private health insurance (Private) |
|---|---|---|
| **Monthly premium basis** | Roughly 16.3% of gross income combined, capped at the contribution ceiling | Fixed premium based on age at entry, health status, and chosen tariff |
| **Family coverage** | Non-earning spouse and children covered at no extra cost | Each family member requires a separate premium |
| **Deductibles / out-of-pocket** | Minimal; most services covered with small co-pays | Deductible options that reduce monthly premiums |
| **Provider access / specialists** | GP referral typically required; longer wait times | Direct specialist access; shorter wait times; chief physician treatment in hospital |
| **Employer subsidy / tax treatment** | Employer pays ~7.3% of gross salary (capped) | Employer pays up to €496.97/month (2026 cap); private health insurance premiums partially tax-deductible |
| **Long-term affordability** | Premiums rise with income and public health insurance rate changes | Premiums tend to rise with age and healthcare inflation; aging reserves help to moderate increases |
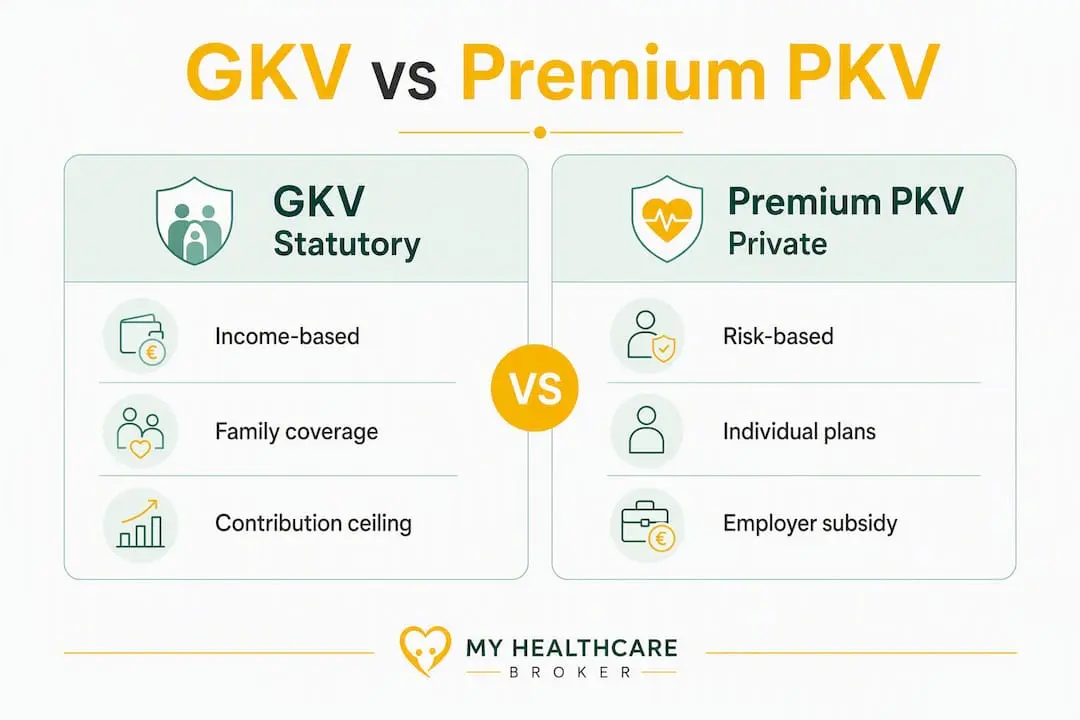
Private health insurance tends to win for young, healthy, high-earning singles and self-employed professionals. Public health insurance usually remains the better option for one-earner families with children, or for anyone approaching age 55 without a long runway to build aging reserves.
Who should consider switching to private health insurance?
Employees above the income threshold
Employees must earn above €77,400 gross per year to be eligible to leave public health insurance (Jahresarbeitsentgeltgrenze (JAEG) for 2026). That threshold must be met for a full calendar year before switching is permitted in most cases, though a significant mid-year pay rise can sometimes accelerate the timeline. If your salary just crossed the line, check with HR before assuming you can switch immediately.
Self-employed professionals
For the self-employed, public health insurance contributions are calculated on full income with no employer sharing the load, which means the statutory system can become expensive quickly. Private health insurance is often structurally cheaper for self-employed earners because premiums are not income-based. A freelancer earning €80,000 a year pays the same private health insurance premium as one earning €120,000, assuming the same age and health profile.
Civil servants (Beamte)
Civil servants receive a government subsidy called Beihilfe, which covers 50–80% of medical costs depending on family status. Private health insurance then covers only the remaining gap, making the net premium very low. For this group, private health insurance is almost always the financially rational choice.
When to hold off on switching
- You have a non-earning spouse and children: per-person private health insurance premiums can easily exceed public health insurance family co-insurance savings.
- You are 50 or older: aging reserves have less time to accumulate, and premiums at entry will already be higher.
- You have significant pre-existing conditions: insurers may apply risk surcharges or exclude conditions entirely.
- You plan to reduce income or return to employment below the JAEG threshold within a few years.
Before getting quotes, collect these data points: your current gross annual salary, your age, your family status and dependents' ages, a summary of any ongoing medical conditions or recent treatments, your employer's confirmed subsidy amount, and your expected career trajectory over the next decade.
Pro Tip: Treat the private health insurance decision like a 20–30 year financial commitment, not a monthly savings exercise. The entry premium looks attractive at 32; the question worth asking is what that premium projects to at 55 and 65, and whether your income at retirement will still support it.
What do private health insurance premiums actually cost, and how does the employer subsidy change the math?
How private health insurance premiums are calculated
Public health insurance charges roughly 16.3% of your gross salary (employer and employee combined) up to the contribution ceiling. Private health insurance works differently: your premium is set at the moment you apply, based on your age, health status, coverage tier, and chosen deductible. Income plays no role. A 34-year-old in good health choosing a mid-tier tariff with a €600 annual deductible will pay a fixed monthly amount that does not increase just because they get a raise.
Typical gross private health insurance premiums for healthy under-40s range within a mid-tier band before the employer subsidy is applied.
The employer subsidy and net cost
Employers contribute up to €496.97 per month (2026 cap) toward a private health insurance premium. This matches the maximum amount they would have paid as their share of public health insurance contributions. If your private health insurance premium is below that cap, the employer subsidy may cover it fully, meaning your net employee share could be very low or zero, though most people choose richer tariffs that push the gross premium higher.
Worked examples
| Profile | Gross private health insurance Premium | Employer Subsidy | Net Employee Cost | Approx. Public health insurance Employee Share |
|---|---|---|---|---|
| Single, age 32, healthy, mid-tier tariff | €280/month | €280/month (capped at actual premium) | €0–€50/month | — |
| Single, under 40, healthy, premium tariff | €380/month | €380/month (employer subsidy up to €496.97/month) | €0–€80/month | — |
| Family: one earner, spouse + 1 child | — | €496.97/month | — | — (family co-insured free) |
The family scenario shows why public health insurance is often cheaper for one-earner families: each additional family member adds a separate private health insurance premium with no additional employer subsidy, while public health insurance covers them at no extra charge. For a detailed Private health insurance vs public health insurance cost comparison tailored to high-income employees, Myhealthcarebroker's breakdown covers the full net-cost model.
Tax treatment
Private health insurance premiums paid for basic coverage (Basisabsicherung) are deductible as Sonderausgaben on your German income tax return, up to statutory limits. The employer subsidy counts as income and is taxable, but the net tax effect is usually positive for high earners. Confirm the exact deductible amount with a Steuerberater (tax advisor), since the deductible portion depends on which elements of your tariff qualify as basic coverage under German tax law.
This article provides general information, not tax or legal advice. Confirm current rules with a qualified tax professional or the Bundeszentralamt für Steuern.
What are the real pros, cons, and long-term risks of going private?
Concrete advantages for high earners
- Faster specialist access: private health insurance cardholders are typically seen more quickly by specialists and can book directly without a GP referral.
- Superior inpatient care: Most premium tariffs include chief physician (Chefarzt) treatment and a single or double room in hospital.
- Dental and vision coverage: private health insurance tariffs routinely cover dental prosthetics, orthodontics, and glasses at levels public health insurance does not approach.
- Tailored coverage: You choose the deductible, the scope of alternative treatments, and international coverage options.
- Potential net savings: For young, healthy, high-earning singles, net monthly costs after the employer subsidy can be materially lower than public health insurance contributions.
Concrete disadvantages to weigh
- Per-person family premiums: Each non-earning dependent needs their own policy. For families, this often erases individual savings entirely.
- Underwriting and exclusions: Insurers assess your health history. Pre-existing conditions may attract risk surcharges or permanent exclusions.
- Age-related premium increases: private health insurance premiums rise with age and healthcare cost inflation. Aging reserves (Altersrückstellungen) help, but they do not eliminate increases.
- No income-linked protection: If your income drops sharply, your private health insurance premium does not. Public health insurance adjusts automatically.
- Portability limits: Aging reserves built with one insurer are not fully portable if you switch providers later.
The age-55 lock: the risk most people underestimate
Switching back from private health insurance to public health insurance after age 55 is legally and practically very difficult under German law. Most financial planners treat a move to private health insurance as effectively permanent for anyone who switches in their 30s or 40s.
German law makes returning to public health insurance nearly impossible after 55 except under narrow conditions, such as dropping below the JAEG threshold through a significant income reduction. If you switch to private health insurance at 35 and your circumstances change at 52, you are almost certainly staying in private health insurance through retirement. That is not a problem if you planned for it; it becomes a serious financial strain if you did not.
How do you actually switch from public health insurance to private health insurance, step by step?
The switching process follows a specific sequence. Skipping steps, or doing them out of order, risks a coverage gap or a recorded rejection that affects future insurability.
- Confirm eligibility. Verify your gross annual salary exceeds €77,400 for 2026, or confirm your self-employed or civil servant status. Ask HR for written confirmation of your annual salary.
- Gather documents. Collect your last three payslips, your current public health insurance membership certificate, a summary of any ongoing medical treatments or prescriptions, and your tax ID.
- Run anonymous pre-inquiries (anonyme Voranfrage). Before submitting any formal application, use anonymous pre-inquiries to test acceptance with multiple insurers. This step is critical: a formal application that gets declined is recorded in central insurer databases and can affect future applications. An anonymous inquiry carries no such risk.
- Submit the formal application with health questionnaire. Once you have a positive signal from the anonymous inquiry, submit the full application. Answer every health question accurately. Misrepresentation can void the policy later.
- Wait for written acceptance (Policierung). The insurer issues a formal policy document. Do not cancel your public health insurance until you hold this document in hand. Cancelling before written acceptance risks a mandatory coverage gap, which is illegal under German law.
- Cancel your public health insurance with the correct notice period. Most statutory insurers require two months' notice to the end of a calendar month. Submit cancellation in writing and request a Kündigungsbestätigung (cancellation confirmation).
- Submit private health insurance proof to your employer. Provide your employer's HR department with your private health insurance policy confirmation so they can adjust payroll and begin paying the employer subsidy directly.
Timing note for employees: If your salary crossed the JAEG mid-year, you may need to wait until January 1 of the following year to switch, unless the threshold was met for the full preceding calendar year. Confirm the exact timing with HR before starting the process.
Pro Tip: Ask HR two specific questions before you start: "What is the exact employer subsidy amount you will pay toward my private health insurance?" and "What date does the payroll system need my private health insurance confirmation to process the subsidy from month one?" Getting these answers in writing prevents payroll delays.
How do you choose the right premium private plan?
Not all private health insurance tariffs are equal, and the cheapest entry premium is rarely the best long-term choice. These criteria separate plans worth considering from those that look good on a comparison sheet but create problems at 55.
What to look for
- Altersrückstellungen (aging reserves): Every serious private health insurance tariff builds reserves to cushion future premium increases. Tariffs without this feature are a red flag. Ask for projected premiums at ages 45, 55, and 65 in writing.
- Dental and vision scope: Check the annual limits and whether dental prosthetics and orthodontics are covered. Public health insurance dental coverage is minimal; this is one of private health insurance's clearest advantages.
- Inpatient options: Chefarzt treatment and single-room accommodation are standard in premium tariffs. Confirm they are included, not optional add-ons.
- Deductible levels: A higher annual deductible (Selbstbeteiligung) lowers your monthly premium and can make sense if you are healthy and rarely use healthcare. Model the break-even point before choosing.
- International coverage: If you travel frequently or work internationally, check whether the tariff covers treatment abroad and for how long.
- Tariff flexibility: Some insurers offer internal tariff switches that let you adjust coverage without a new health assessment. This matters if your circumstances change.
Red flags to avoid
- Tariffs with no Altersrückstellung or vague language about future premium projections.
- Exclusions written so broadly that common conditions (back pain, mental health) are permanently excluded.
- Insurers who cannot provide a written projected premium table at ages 45, 55, and 65.
- Brokers who present only one insurer's options without explaining why alternatives were ruled out.
Questions to ask any insurer or broker
- "What is the projected monthly premium for this tariff at ages 45, 55, and 65, assuming standard healthcare inflation?"
- "Which conditions from my health questionnaire will be excluded, and are any exclusions negotiable?"
- "Does this tariff include an internal downgrade option if I need to reduce costs later?"
- "Can I see the full policy wording (Versicherungsbedingungen) before I sign?"
- "What waiting periods apply to dental and specialist treatments?"
Request projected premium tables, sample policy wording, a full list of exclusions, and confirmation of waiting periods in writing before committing. Understanding what private health insurance actually covers across dental, vision, and inpatient care helps you compare tariffs on substance rather than headline price.
Real-world scenarios: how the numbers play out in practice
Scenario 1: Single high earner, age 32
A software engineer earning €90,000 gross annually, healthy, no dependents. A mid-tier private health insurance tariff costs roughly €280/month gross. The employer subsidy for 2026 covers up to €496.97/month, so the net employee cost is effectively €0 on this tariff. The public health insurance employee contribution at this income would be approximately €380–€420/month. Net monthly saving: roughly €380–€420. The decisive factor here is the employer subsidy absorbing the full premium, making private health insurance clearly the better financial choice.
Scenario 2: One-earner family, two children
One parent earns €95,000; the other does not work. Two children, ages 4 and 7. Private health insurance gross premiums: €320 (earner) + €180 (spouse) + €120 + €110 (children) = €730/month. Employer subsidy for 2026: €496.97/month. Net employee cost: ~€233/month. Public health insurance employee contribution: ~€390–€420/month with spouse and children co-insured at no extra charge. The net private health insurance cost is still lower here, but the margin is narrow, and any health issue affecting the non-earning spouse or children that triggers a risk surcharge could flip the calculation.
Scenario 3: Self-employed, age 35
A freelance consultant earning €75,000 net annually. In public health insurance, self-employed pay both employer and employee shares, roughly 16.3% of assessed income, which can reach €700–€800/month or more depending on the Krankenkasse's Zusatzbeitrag. Private health insurance for the self-employed is often structurally cheaper because the premium is fixed at entry and does not scale with income. A healthy 35-year-old freelancer might pay €320–€380/month for a solid private health insurance tariff, with no employer subsidy but a significant saving versus full public health insurance contributions. The decisive factor: income stability. If consulting income drops sharply, the private health insurance premium does not.
| Profile | Gross private health insurance Cost | Net Monthly Cost | Public health insurance Equivalent | Annual Saving (est.) |
|---|---|---|---|---|
| Single, age 32, employee | €280/month | ~€0–€50/month | ~€390/month | — |
| Family (1 earner, 2 kids) | €730/month | ~€233/month | ~€390/month | — |
| Self-employed, age 35 | — | — (no subsidy) | — | — |
These figures are illustrative examples based on typical 2026 premium ranges and the €496.97/month employer subsidy cap. Actual premiums depend on health status, chosen tariff, and insurer. Complex family or health situations always warrant bespoke broker modeling.
Key Takeaways
Switching from public health insurance to a premium private health insurance plan makes clear financial sense for young, healthy, high-earning singles and self-employed professionals, but the family-cost model and the age-55 lock make it a decision that demands careful, long-term planning.
| Point | Details |
|---|---|
| JAEG threshold for 2026 | Employees must earn above €77,400 gross per year to be eligible to leave public health insurance (Jahresarbeitsentgeltgrenze (JAEG) for 2026). |
| Employer subsidy impact | The employer contributes up to €496.97/month, often reducing net private health insurance cost below public health insurance contributions for singles. |
| Family cost warning | Each dependent needs a separate private health insurance premium; public health insurance co-insures non-earning family members for free. |
| Age-55 lock | Switching back to public health insurance after 55 is legally and practically very difficult; treat the decision as long-term. |
| Myhealthcarebroker | Independent English-language broker guidance, anonymous pre-inquiries, and plan comparison across major German private health insurance insurers. |
What I tell clients before they decide
The single question I ask every client considering a move to private health insurance is this: "What does your life look like at 60?" Not at 35, when the premium looks attractive and the employer subsidy covers most of it. At 60, when premiums have risen, when family circumstances may have changed, and when switching back is no longer a realistic option.
Most people who regret a private health insurance switch made one of two mistakes. They modeled only the entry premium, not the projected premium at retirement age. Or they switched as a single person and then had children, discovering too late that the per-person premium model erases the savings they planned around.
The clients who are genuinely well-served by private health insurance share a few traits: they are under 40, in good health, earning well above the JAEG, and either single or in a dual-income household where both partners can carry their own premium. Civil servants with Beihilfe are almost always better off in private health insurance, full stop.
What I consistently recommend, regardless of how clear-cut a situation looks: get at least two insurer quotes through anonymous pre-inquiries, request projected premium tables at ages 45, 55, and 65 in writing, and have an independent broker run the household-level numbers, not just the single-person arithmetic. The entry premium is the easy part. The 30-year projection is where the real decision lives.
Useful sources and where to get help
These resources cover the official rules, practical switching steps, and tools to model your own numbers.
- Public health insurance vs private health insurance 2026: Private Health Insurance in Germany Explained — Covers the 2026 JAEG threshold, employer subsidy mechanics, and cost comparisons. Useful for checking the current figures before you run your own numbers.
- [private health insurance vs public health insurance Cost Comparison for High Earners](/blog/pkv-versus-gkv-cost-comparison-high-income) — Myhealthcarebroker's detailed cost model for high-income employees, including net-cost calculations after employer subsidy and tax effects.
- [Switch to Private Health Insurance Germany](/blog/how-to-switch-from-public-to-private-health-insurance-in-germany) — Myhealthcarebroker's eligibility checker and switching guide, in plain English.
- [What Does Private Health Insurance Cover in Germany?](/what-does-private-health-insurance-cover) — Explains dental, vision, inpatient, and specialist coverage under private health insurance tariffs. Useful when comparing tariff scope.
- [International Freelancer Health Insurance in Germany](/health-insurance-freelancer-expats-germany) — Tailored guidance for self-employed and freelance professionals evaluating private health insurance.
- [Private Health Insurance Calculator Germany](/calculator) — Myhealthcarebroker's interactive tool to model your net monthly cost after employer subsidy and tax effects. The fastest way to see whether private health insurance makes financial sense for your specific situation.
Myhealthcarebroker makes the private health insurance switch straightforward for high earners
Comparing private health insurance tariffs across German insurers, in German, while managing a full-time job, is where most people stall. Myhealthcarebroker removes that friction entirely. As an independent broker not tied to any single insurer, Myhealthcarebroker compares plans across all major German private health insurance providers, runs the household-level cost model for your specific situation, and guides you through the anonymous pre-inquiry and formal application process in clear English.
For high-earning employees, self-employed professionals, and civil servants, the service is free: Myhealthcarebroker is paid a regulated commission by the insurer when you sign up, so you get independent advice without a fee. The process covers everything from your first eligibility check through to employer payroll coordination and ongoing support after the policy starts.
If you are ready to see what your net monthly private health insurance cost would look like after the employer subsidy, use the Myhealthcarebroker calculator to run the numbers now. Or, if you want to talk through your specific situation with an English-speaking advisor, visit the main broker page to book a consultation.
Recommended
- Private health insurance vs public health insurance Cost Comparison for High Earners (2026)
- Private health insurance Premium Optimization for High Earners in Germany
- Private health insurance Premium Rebate for a Healthy Year in Germany
- Compare Private Health Plans in Germany: 2026 Guide
Written by Marco Maurelli, editorial lead ·
Reviewed by Bettina Ostermann, insurance broker
(§ 34d Abs. 1 GewO) · Last reviewed: 2026-08-12
*This article is general information, not individual advice. Your age, income,
residence status and health history change the answer. Get a free quote
or book a consultation before you decide.*
*Myhealthcarebroker is an insurance broker registered under § 34d GewO.
See our initial information and imprint.*
*Parts of this article were drafted with AI assistance and reviewed by a
licensed broker. Images marked "AI-generated" were created with generative AI.*
 Written and reviewed byBettina Ostermann